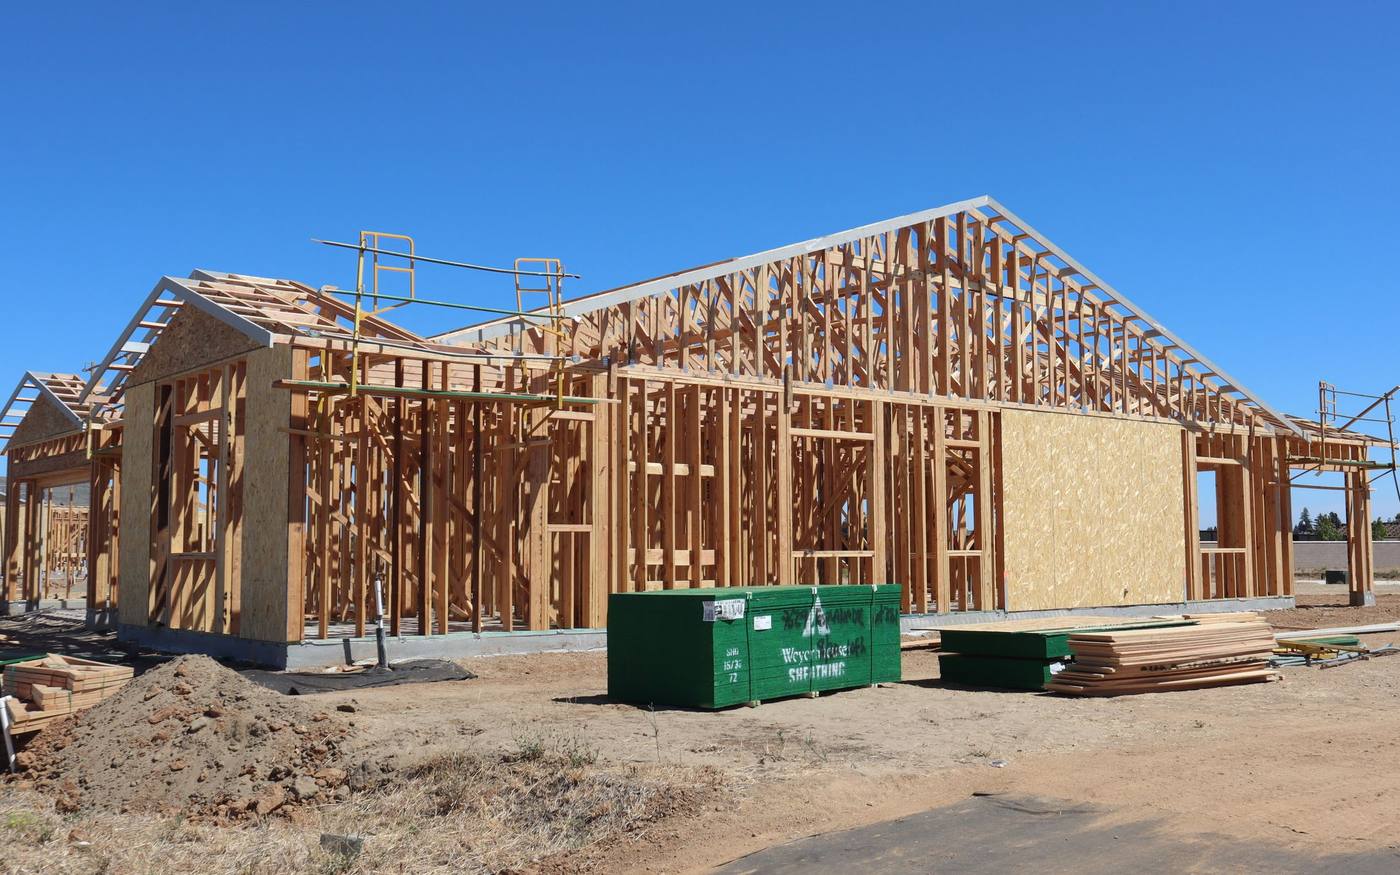
This engagement reached us as a referral from a residential mortgage broker. His client owned a parcel of development land in the North Okanagan with approval for a small phased residential project, and the financing he needed sat on the commercial side of the line, outside what a residential brokerage places.
The land was already financed, on private money administered through a trust company. That is a normal place for a developer to start: raw land produces no income, so most institutional lenders will not lend against it, and private lenders fill the gap. It is expensive to hold, though, and it does nothing to pay for construction. The client needed to retire that loan and get the first phase built, and he had not financed a phased development before.
A phased project asks one lender to carry two different exposures at the same time. The land facility has to live for the length of the whole project, secured against ground that gets sold off one phase at a time. The construction facility is short, drawn against work in place on a single phase and repaid when that phase sells. Plenty of lenders are comfortable with one and not the other, and splitting them between two lenders means negotiating who ranks where, on security that changes as lots sell.
We prepared the financing request around the whole sequence rather than the first phase on its own, and took it to lenders we knew would look at the land and the construction together.
Greater flexibility: we were able to place both facilities with a single credit union. The land loan was set at $600,000, repaid from the net sale proceeds of each phase as it sells and held within 50% of the value of the land still remaining. It was written for a two-year term with options to extend in twelve-month increments, where the engagement had contemplated twelve months. The Phase 1 construction loan came in at $977,760, advanced on progress draws against work in place, and above the amount we set out to secure. Both facilities are priced at prime plus 2.00%.
Both loans also fund their own interest. The credit union carved an interest reserve out of each advance, twenty-four months on the land and twelve on the construction loan, so the project pays its carrying cost out of the loan instead of out of the developer's working capital. The balance of the land advance went back to the client to start Phase 1.
If you are holding development land on private money and working out how to pay for the first phase, the structure matters as much as the rate. Start with a 15-minute commercial debt review and we will benchmark your pricing, covenants, guarantees, collateral and available leverage against what we are seeing in the market right now.